

Market insight: Intention-action gap holding back bioplastics transition

Driven by tightening environmental regulations and corporate sustainability targets, global product and packaging leaders are showing strong interest in accelerating the transition to bio-based plastics, according to the newly released THINK NEGATIVE: Bio-Based Advantage Report by Braskem.
To “think negative” is to seek solutions that drive down carbon emissions, cut waste, and mitigate the impact of plastics—a mindset effectively supported by bio-based alternatives.
The THINK NEGATIVE: Bio-Based Advantage Report reveals that companies plan to increase bio-based plastic investment but are hindered by external barriers. (Source: Braskem)
For this study, the Brazilian plastics producer surveyed 2,250 industry decision-makers across 14 countries. The findings reveal that although 75% of respondents plan to boost bioplastics investments over the next two to three years and 16% are actively considering a purchase, actual procurement remains hindered by high costs, performance concerns, and processing complexities.
This investment intent is heavily backed by regulatory and corporate mandates: 82% of respondents rated legislative compliance as important or very important, while 49% cited corporate targets as the initial trigger for considering alternative plastics.
However, a clear gap remains between intention and action. Braskem noted that 70% of respondents had not yet reached the purchasing stage, with 97% identifying external factors as barriers to adoption.
Financial hurdles are the most prevalent, with 35% worried about higher costs. According to Braskem, bio-based plastics have traditionally carried a 20-50% price premium over conventional plastics.
Additionally, 32% of respondents expressed concerns regarding quality and performance, while 25% cited the processing complexity of switching from conventional materials to bioplastics as a barrier.
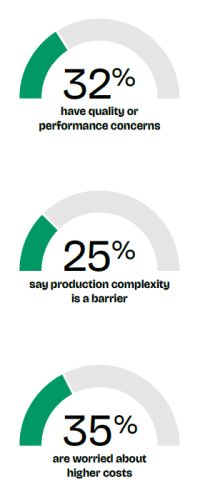
Performance anxiety, production complexity, and cost concerns are barriers to companies adopting bioplastics. (Source: Braskem)
The hidden cost of the status quo
The report reminds us that the adoption of sustainable materials remains bottlenecked by financial considerations. However, Braskem contends that evaluating bioplastics strictly through the lens of upfront price premiums is a strategic oversight.
Companies that adhere to fossil-based plastics face escalating hidden challenges, including reputational risks among consumers, tightening plastic packaging regulations, and volatile petrochemical supply chains driven by geopolitical tensions.
Unlike finite fossil resources, renewable feedstocks are replenished with every growing season. By diversifying into bio-based plastics, companies secure a predictable raw material supply that reduces geopolitical risks and fosters confident, long-term strategic planning.
Ultimately, the “bio-based advantage” is a long-term approach designed to future-proof business models against unavoidable regulatory and market impacts.
Drop-ins vs. novel polymers
The report reflects a market divided by application requirements, asking decision-makers to choose between two primary bio-based material sectors:
· Bio-based drop-in plastics (e.g., Bio-PE, Bio-PET): Chemically identical or highly similar to their fossil-based counterparts, these drop-in plastics require little to no modification to existing production lines and recycling infrastructure. This seamless integration has sparked rapid interest from mass-market brands.
However, because biodegradability depends on a polymer's chemical structure rather than the origin of its raw materials, these drop-ins are not biodegradable.
· Novel polymers (e.g., PLA, PHA): Sectors targeting circular food packaging are increasingly pivoting toward materials like PLA and PHA, as they address food contamination concerns and are biodegradable. While PLA is technically biodegradable, it requires industrial composting facilities to break down. PHA, produced through bacterial fermentation, can degrade naturally in home compost piles and marine environments.
However, processing requirements differ between certain bioplastics and conventional polymers. For instance, PLA cannot tolerate temperatures above 210°C without compromising its final mechanical properties, whereas PE can. Additionally, PLA pellets readily absorb moisture, necessitating pre-drying processes that PE pellets can forgo.
The path forward
The THINK NEGATIVE: Bio-Based Advantage Report echoes a broader industry consensus on the remaining steps toward universal bioplastics adoption. It underscores that the primary barrier is no longer technological capability; rather, achieving true market scale now requires moving beyond corporate commitments alone.
Crucially, this industrial scaling is already underway. According to the latest data from European Bioplastics (EUBP), global bioplastics production capacity is projected to double from 2.31 million tons in 2025 to approximately 4.69 million tons by 2030.
With the growth of this expanding market, the equation changes for forward-thinking companies navigating current operational challenges: the transition is no longer a question of “if”, but “how fast”.
These companies must firmly believe that investing in long-term collaborations and circularity today will secure a decisive competitive advantage, empowering them to sustain their momentum and continue in this green transition journey.
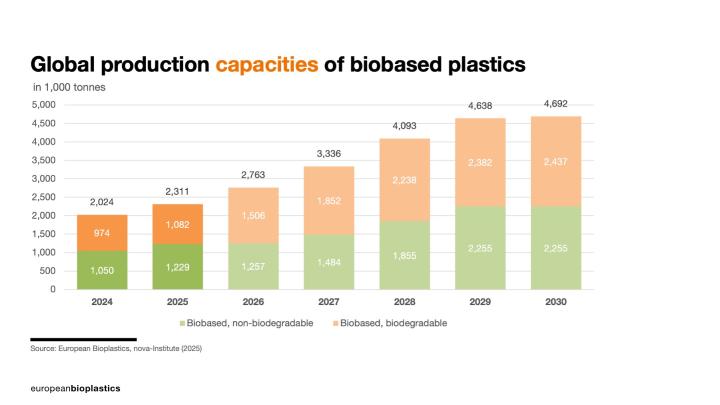
The global bioplastics production capacity is projected to double by 2030. (Source: EUBP)